
Surgical Sutures Market to Reach USD 7.03 Billion by 2031 as Demand for Absorbable Sutures and Infection-Control Solutions Grows
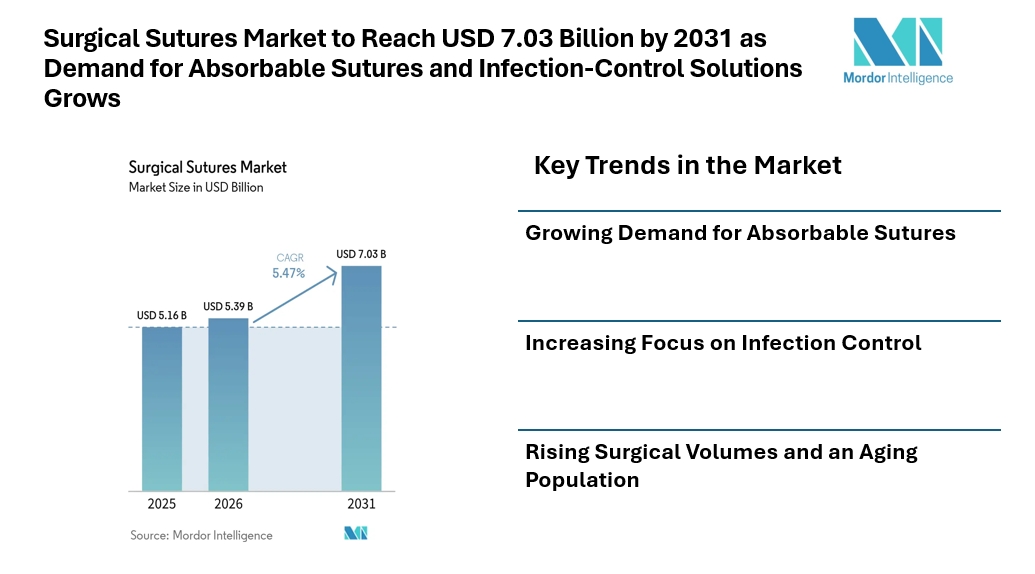
Hyderabad, India – 9 october, 2026 – According to Mordor Intelligence, the Surgical Sutures Market is expected to grow from USD 5.39 billion in 2026 to USD 7.03 billion by 2031, registering a CAGR of 5.47% during the forecast period. Market growth is supported by rising surgical procedure volumes, an aging population, the growing burden of chronic diseases, and increasing demand for surgical closure products that support infection control and efficient postoperative care.
The surgical sutures market is benefiting from the growing use of absorbable sutures, antimicrobial-coated filaments, and synthetic materials designed to support wound closure and tissue healing. Hospitals and ambulatory surgical centers are increasingly adopting suture products that can reduce the need for follow-up removal procedures and support operating-room efficiency. At the same time, expanding healthcare infrastructure in emerging economies is creating additional demand across surgical specialties.
According to the market forecast, North America remains the largest regional market, while Asia-Pacific is expected to record the fastest growth. However, competition from surgical staplers, tissue adhesives, and robotic closure systems, alongside raw-material supply disruptions, may create challenges for manufacturers.
Report Overview: https://www.mordorintelligence.com/industry-reports/surgical-sutures-market?utm_source=abnewswire
Surgical Sutures Market Trends
Growing Demand for Absorbable Sutures
Absorbable sutures are an important part of the surgical sutures market as healthcare providers seek closure materials that break down naturally during the healing process. These products can reduce the need for suture-removal appointments and are used across several surgical applications. Their use supports hospital efforts to simplify postoperative care and improve procedural efficiency.
Synthetic absorbable materials, including polyglycolic acid and polydioxanone, are gaining attention because their properties can be suited to different tissue-healing requirements. Continued demand for surgical procedures and a preference for predictable wound-closure performance are supporting the adoption of these products.
Increasing Focus on Infection Control
Infection prevention remains a key consideration in surgical wound closure. Antimicrobial-coated sutures are attracting attention because they are designed to help reduce bacterial colonization around surgical sites. Healthcare providers are assessing suture products based on their suitability for infection-control protocols, clinical requirements, and patient needs.
Monofilament sutures are also gaining traction in settings where infection prevention is a priority. Their structure makes them an important option for procedures in which minimizing bacterial retention is a consideration. However, antimicrobial coatings face regulatory scrutiny, encouraging manufacturers to balance product performance with safety and compliance requirements.
Rising Surgical Volumes and an Aging Population
An aging population and the growing burden of chronic diseases are contributing to demand for surgical procedures. Orthopedic, cardiovascular, and other interventions require reliable wound closure, supporting the need for sutures across hospitals and surgical facilities.
Elective procedures and the expansion of surgical services are also contributing to market demand. As healthcare systems manage increasing procedural volumes, providers are looking for products that meet clinical requirements while supporting efficient operating-room workflows.
Expansion of Ambulatory Surgical Centers
The growing role of ambulatory surgical centers is creating opportunities for surgical suture manufacturers. These facilities require products that support efficient procedures, consistent performance, and streamlined patient care. Fast-absorbing sutures and pre-sterilized product formats can align with the operational needs of outpatient surgical settings.
Healthcare infrastructure expansion in emerging economies is another factor supporting demand. Investments in hospital capacity and surgical services are creating opportunities for suppliers across different product categories and applications.
Surgical Sutures Market Segmentation
The surgical sutures market is segmented by product, filament structure, source, coating, application, end user, and geography.
-
By Product
-
Absorbable Sutures
-
Non-absorbable Sutures
-
By Filament Structure
-
Monofilament Sutures
-
Multifilament Sutures
-
By Source
-
Natural Sutures
-
Synthetic Sutures
-
By Coating
-
Coated Sutures
-
Uncoated Sutures
-
By Application
-
Cardiovascular Surgery
-
General Surgery
-
Orthopedic Surgery
-
Gynecology and Obstetrics
-
Ophthalmic Surgery
-
Dental Surgery
-
Plastic and Reconstructive Surgery
-
Other Applications
-
By End User
-
Hospitals
-
Ambulatory Surgical Centers
-
Specialty Clinics
-
Other End Users
-
By Geography
-
North America: United States, Canada, and Mexico
-
Europe: Germany, France, United Kingdom, Italy, Spain, and Rest of Europe
-
Asia-Pacific: China, Japan, India, South Korea, Australia, and Rest of Asia-Pacific
-
Middle East and Africa: GCC, South Africa, and Rest of Middle East and Africa
-
South America: Brazil, Argentina, and Rest of South America
Surgical Sutures Market Competitive Landscape
The surgical sutures industry includes established medical device companies and specialized manufacturers competing across product categories and surgical applications. Companies are focused on maintaining product quality, expanding their portfolios, and meeting the requirements of hospitals, ambulatory surgical centers, and specialty healthcare providers.
Manufacturers are also responding to demand for absorbable materials, monofilament designs, and antimicrobial-coated products. Meanwhile, procurement consolidation and bundled purchasing arrangements are increasing pricing pressure, encouraging suppliers to strengthen their product offerings and distribution capabilities. Competition from staplers, sealants, and robotic closure systems remains an important consideration for market participants.
Key Players
The major companies operating in the surgical sutures market include:
-
B. Braun Melsungen AG
-
Johnson & Johnson
-
Medtronic plc
-
Smith & Nephew plc
-
Teleflex Incorporated
-
Assut Medical Sàrl
-
Boston Scientific Corporation
-
CONMED Corporation
-
DemeTech Corporation
-
Internacional Farmacéutica
-
Kono Seisakusho Co., Ltd.
-
Lotus Surgicals Pvt Ltd
-
Mellon Medical B.V.
-
Meril Life Sciences
-
Peters Surgical
-
Samyang Biopharm
-
Surgical Specialties Corporation
-
Sutures India (Healthium)
-
W. L. Gore & Associates
For more insights on the Japanese market report, please visit the Mordor Intelligence page: https://www.mordorintelligence.com/ja/industry-reports/surgical-sutures-market?utm_source=abnewswire
Conclusion
The surgical sutures market is expected to maintain growth as surgical procedure volumes increase and healthcare providers continue to prioritize effective wound closure, infection prevention, and efficient postoperative care. Demand for absorbable sutures, monofilament designs, synthetic materials, and antimicrobial-coated products is shaping product development and purchasing decisions.
North America remains a key market, while Asia-Pacific offers growth opportunities through expanding healthcare infrastructure and rising surgical demand. Manufacturers that address clinical requirements, regulatory expectations, supply-chain challenges, and changing procurement practices will remain important participants in the competitive surgical sutures industry.
About Mordor Intelligence
Mordor Intelligence is a global market intelligence firm, founded in 2014, helping businesses make informed decisions through data-driven insights, industry expertise, and advanced analytics. With 550+ domain experts and on-ground specialists across 150+ countries, the company delivers comprehensive intelligence across aerospace & defense, agriculture, automation, automotive, chemicals & materials, consumer goods & services, electronics, energy & power, financial services, food & beverages, healthcare, hospitality & tourism, information & communications technology, and logistics.
Its offerings include syndicated industry reports and subscription platforms such as Synapse. Mordor Intelligence is ISO 9001:2015 and ISO/IEC 27001:2022 certified, a member of ESOMAR and the Market Research Society of India, and a four-time Great Place to Work® honoree. Learn more at mordorintelligence.com.
Media Contact
Company Name: Mordor Intelligence Private Limited
Contact Person: Jignesh Thakkar
Email: Send Email
Phone: +1 617-765-2493
Address:11th Floor, Rajapushpa Summit, Nanakramguda Rd, Financial District, Gachibowli
City: Hyderabad
State: Telangana 500008
Country: India
Website: https://www.mordorintelligence.com/


